
Drive Select Finance compares 30+ lenders to secure vehicle and asset finance rates from 5.68% p.a., with fast 24-48 hour approvals and zero credit score impact on initial quotes for customers across Australia. Financing a truck or heavy vehicle is different to a standard car loan. We cover lender options, finance structures, interest rates, and how to get your truck loan approved.
Whether you're purchasing your first prime mover, adding a rigid to your fleet, or upgrading an ageing tipper, securing the right truck loan is critical to your business operations. Commercial vehicle finance is more complex than a standard car loan — but with the right broker, the process is straightforward and the outcomes are highly competitive.
What Types of Vehicles Are Covered by Truck Loans?
Commercial vehicle finance covers a broad range of assets:
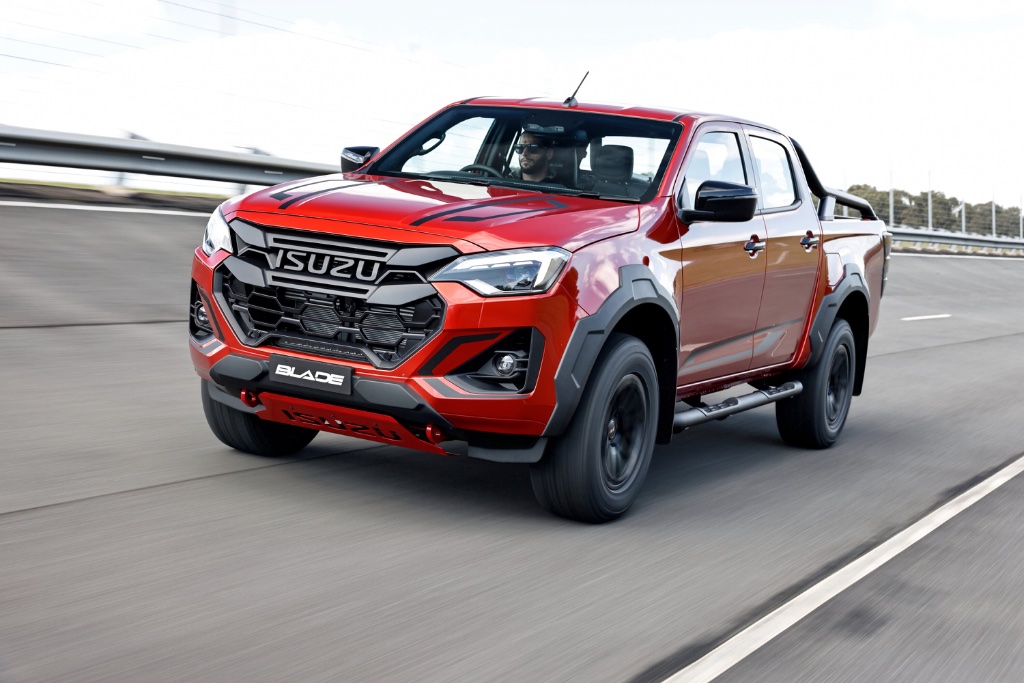
- Light commercial (up to 4.5t GVM): Utes, vans, small trucks — Toyota HiLux, Ford Ranger, Isuzu NPR, etc.
- Medium commercial (4.5t – 12t GVM): Tippers, curtainsiders, refrigerated vehicles — Hino, UD, Fuso, etc.
- Heavy commercial (12t+ GVM): Prime movers, B-doubles, semi-trailers — Kenworth, Volvo, DAF, Western Star, etc.
- Trailers: Including semi-trailers, flat-tops, tankers, refrigerated, and B-trains.
- Specialised vehicles: Concrete agitators, tow trucks, crane trucks, and other specialist applications.
Loan Structures for Truck Finance
Chattel Mortgage
The most common structure for truck finance. You take ownership from day one, interest is tax deductible, and GST is claimable upfront for GST-registered businesses. A balloon payment can be structured to align with expected resale value, reducing monthly repayments.
Finance Lease
The lender owns the vehicle. You make fixed lease payments and have options at the end of the term: purchase at residual, trade, or return. Favoured by fleet operators and businesses who prefer operating lease treatment for accounting purposes.
Commercial Hire Purchase
Similar to chattel mortgage in that you take ownership at term end, but structured as a hire arrangement. Some businesses prefer this for GST accounting reasons. Your accountant can advise on which suits your structure.
Rental / Operating Lease
Full off-balance-sheet treatment. Fixed monthly payments including maintenance packages. Common in large fleet applications. The lender bears the residual value risk.
💡 Balloon Payment Strategy
Setting a balloon at 20–30% reduces monthly repayments significantly. For example, on a $150,000 truck loan over 5 years at 8%, a 25% balloon reduces monthly repayments by approximately $400/month. Ensure the balloon aligns with realistic market value at term end.
Truck Loan Rates in Australia
Commercial vehicle loan rates vary based on the asset, borrower profile, and lender. Indicative ranges in 2026:
- Prime applicant, new truck: 7% – 10% p.a.
- Good profile, used truck: 8.5% – 13% p.a.
- Low-doc / self-employed: 9% – 15% p.a.
- Older assets (7+ years): 12% – 18% p.a.
Specialist lenders and non-bank financiers often provide more competitive rates on heavy commercials than the major banks, particularly for assets with high residual values like quality prime movers.
What Lenders Assess for Truck Finance
Commercial lenders look at a combination of factors:
- Business financials: Profit and loss, BAS statements, bank statements — demonstrating ability to service the debt.
- ABN age: Most lenders prefer 12+ months of trading history. Start-up lenders do exist but rates are higher.
- Asset quality: Age, condition, brand, and residual value of the truck or trailer.
- Industry experience: Lenders look more favourably on operators with established industry experience and contracts.
- Credit history: Personal credit of directors/guarantors is also assessed.
- Security: The truck itself is the primary security. Additional property security can unlock lower rates.
Low-Doc Truck Loans for Self-Employed Operators
Not all owner-operators have clean, up-to-date financial statements. Low-doc truck loans assess applications based on:
- 6 months of business bank statements
- BAS statements (2–4 quarters)
- Self-declaration of income
- Accountant's letter
Drive Select Finance has access to specialist commercial lenders who approve low-doc truck loans — including for start-up operators with relevant industry experience.
Buying a New vs Used Truck
New Trucks
Lower rates, manufacturer's warranty, maximum depreciation benefits, and predictable maintenance costs. OEM finance programs can occasionally offer promotional rates but rarely beat broker-sourced options on the full cost of credit.
Used Trucks
Lower acquisition cost, but higher rates and more lender scrutiny on age and condition. Most lenders cap used truck finance at 10–15 years old at loan end. Ex-lease and ex-fleet trucks from reputable sources offer excellent value.
How to Apply for a Truck Loan
Apply online with Drive Select Finance. Indicate that you need commercial vehicle or truck finance. Our brokers have specialist knowledge in commercial lending and will identify the optimal lender, structure, and rate for your specific vehicle and business situation.
Documentation required at formal application stage: ABN/ACN, ID, business financials or bank statements, and vehicle details. We handle the rest.
Get a free, no-obligation quote today
30+ lenders compared. No credit impact. Expert brokers ready to help.